Nonprofit expense reporting best practices for 2026: sort expenses by nature and function, see what's allowable, map them to Form 990, and report monthly.
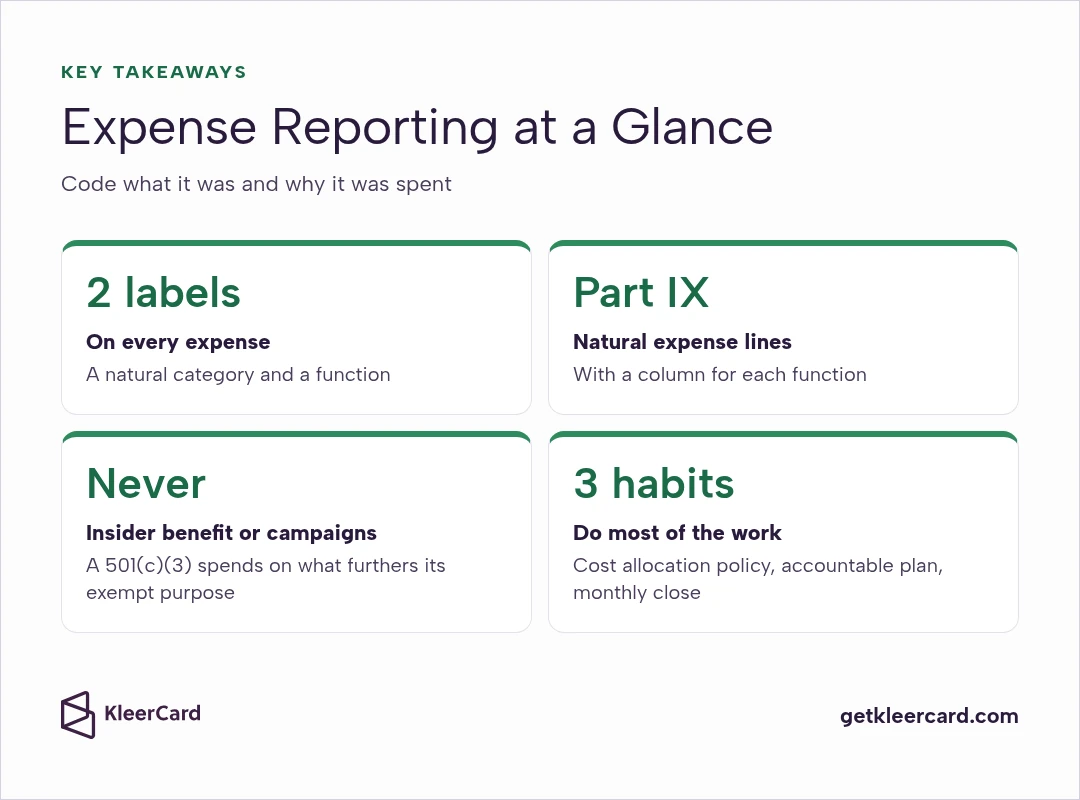
Nonprofit expense reporting sorts every expense two ways: by nature, meaning what was bought, such as salaries, rent, or supplies, and by function, meaning why it was spent (program services, management and general, or fundraising). On the full Form 990, 501(c)(3) organizations report both in Part IX, the statement of functional expenses.
If expense reporting feels like a burden, a few setup changes usually lighten it, and the fundamentals are simpler than they look. Like all nonprofit organization accounting, expense reporting answers to a stewardship standard: you're tracking what was spent and showing donors, grantors, auditors, and the IRS that every dollar served your mission.
I help churches, schools, and nonprofits set up how their spending gets coded, and the pattern I see most is simple. Expenses that get a category and a function the day they happen are easy to report, while the ones that wait until December are where the hours go.
For-profit companies report expenses for tax and investor purposes. Nonprofits report them to demonstrate stewardship. Functional expense reporting splits costs into program services, management and general, and fundraising, so donors can see how much of their gift funds programs versus overhead.
That distinction matters when donors decide where to give and when grantors decide who to fund. Charity watchdogs analyze these ratios closely, and anyone can look them up on your public Form 990, so getting them right builds long-term credibility.
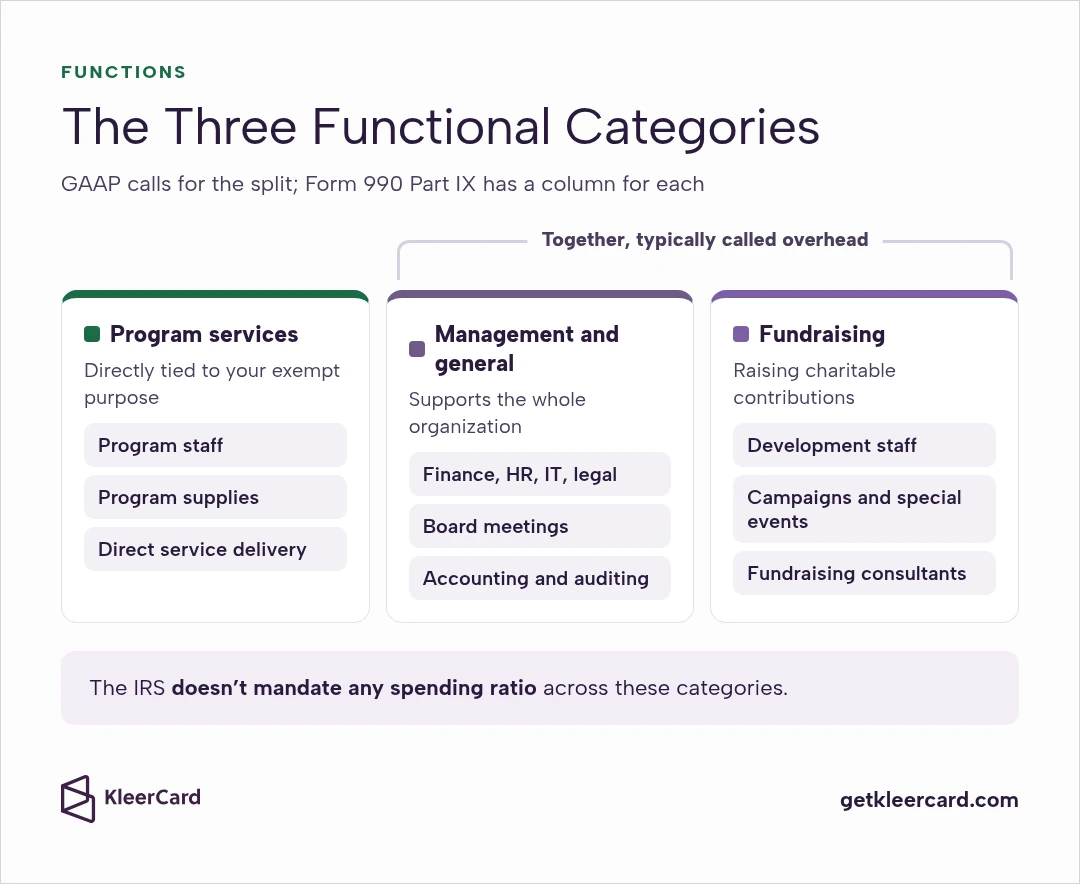
Nonprofit expense reporting starts with classifying every cost into three functional categories: program services, management and general, and fundraising. GAAP calls for this split, and Form 990 Part IX asks 501(c)(3) and 501(c)(4) filers to complete a column for each.
Program services expenses directly relate to your exempt purpose, such as program staff, program supplies, and direct service delivery. If you operate a food pantry, the food and the staff serving it belong here. If you run youth mentorship sessions, the direct costs of those sessions are program expenses.
Salaries require careful allocation. If an employee spends half their time supervising a program and half on general management, half their salary goes to program services and half to management and general. Time studies and activity logs are a well supported way to document these splits.
Management and general expenses cover administrative costs such as finance, HR, IT, legal, and governance that support the whole organization. These overhead costs are necessary and legitimate, even when donors equate lower overhead with greater effectiveness.
The Form 990 instructions name several costs that belong here, including board and committee meetings, general legal services, accounting, auditing, general liability insurance, and office management.
Fundraising expenses cover the costs of raising charitable contributions, including development staff, campaigns, special events, and fundraising consultants.
Together, management and general plus fundraising make up what is typically called overhead. The IRS doesn't mandate any specific spending ratio across these categories, but charity evaluators and many major donors watch these numbers closely.
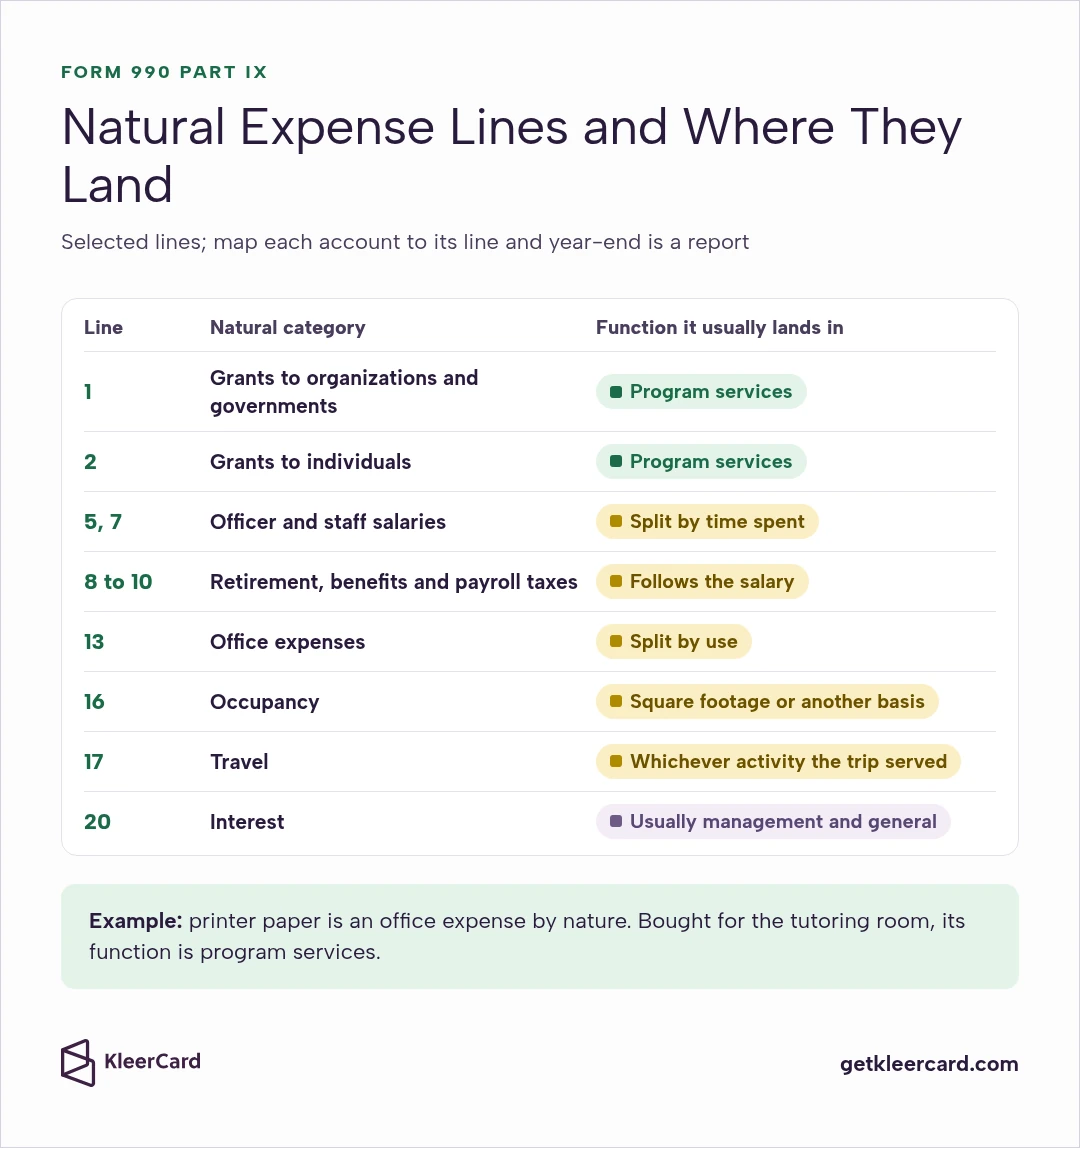
Natural categories answer the other question: what did you buy? Most nonprofits use a list close to the lines on Form 990 Part IX, which makes year-end reporting a matter of adding up accounts rather than reclassifying them.
| Natural expense category | Form 990 Part IX line | What usually goes here | Function it usually lands in |
|---|---|---|---|
| Grants to organizations and governments | Line 1 | Grants your nonprofit pays to other domestic organizations | Program services |
| Grants to individuals | Line 2 | Scholarships, stipends, and direct assistance to people | Program services |
| Compensation of officers and key employees | Line 5 | Pay for the executive director and other listed leaders | Split by time spent |
| Other salaries and wages | Line 7 | Pay for all other employees | Split by time spent |
| Retirement contributions | Line 8 | Employer share of 401(k), 403(b), and pension plans | Follows the salary it relates to |
| Other employee benefits | Line 9 | Health, life, and disability insurance for staff | Follows the salary it relates to |
| Payroll taxes | Line 10 | Employer share of payroll taxes | Follows the salary it relates to |
| Fees for services | Lines 11a to 11g | Management, legal, accounting, lobbying, professional fundraising, investment management, and other contractor fees | Accounting and general legal fees go to management and general; professional fundraising fees go to fundraising |
| Advertising and promotion | Line 12 | Ads, promotional materials, and printed appeals | Whichever function the message supports |
| Office expenses | Line 13 | Supplies, phones, postage, shipping, equipment rental, bank fees, and general printing | Split by use |
| Information technology | Line 14 | Software, hardware, and IT support | Split by use |
| Occupancy | Line 16 | Rent, utilities, and building costs for your own space | Split by square footage or another reasonable basis |
| Travel | Line 17 | Transportation, lodging, and meals while traveling | Whichever activity the trip served |
| Conferences, conventions, and meetings | Line 19 | Registration fees and meeting costs | Whichever activity the event served |
| Interest | Line 20 | Interest on loans and lines of credit | Usually management and general |
| Depreciation | Line 22 | The yearly cost of buildings, vehicles, and equipment | Split by use |
| Insurance | Line 23 | Property and liability coverage that isn't an employee benefit | General liability goes to management and general |
| Other expenses | Line 24 | Anything that doesn't fit above, listed by type | Depends on the expense |
Form 990 also has lines for benefits paid to members, compensation of disqualified persons, royalties, travel for public officials, and payments to affiliates. Most organizations rarely use them.
Read the table across and you have a working chart of expenses. A box of printer paper is an office expense by nature. If it was bought for the after-school tutoring room, its function is program services.
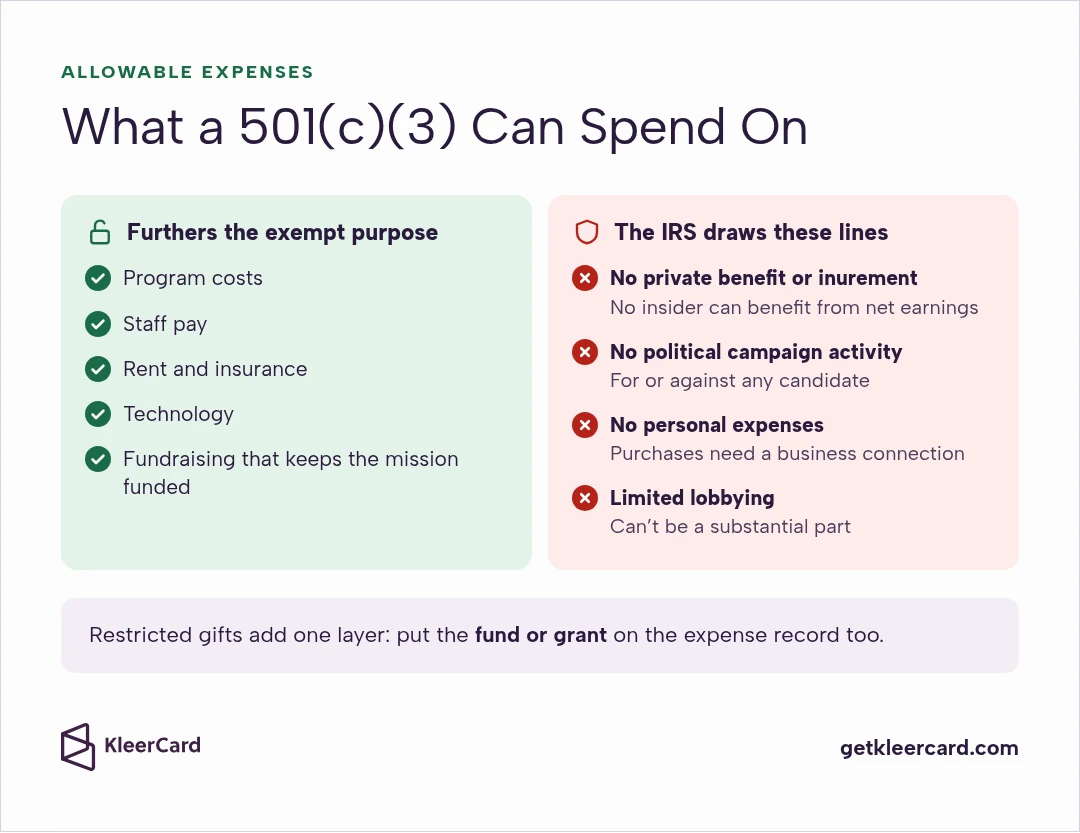
A 501(c)(3) can spend money on anything that furthers its exempt purpose. That covers program costs, staff pay, rent, insurance, technology, and the fundraising that keeps the mission funded.
The IRS exemption requirements draw a few clear lines around that:
Restricted gifts and grants add one more layer. Money given for a specific purpose has to be spent on that purpose, so the fund or grant belongs on the expense record alongside its category and function.
An expense report needs enough detail that someone outside the transaction can code it and an auditor can follow it. This layout works for card purchases, reimbursements, and bills.
| Date | Payee | Description and purpose | Natural category | Function | Fund or grant | Amount | Receipt |
|---|---|---|---|---|---|---|---|
| Example: 3/4 | Office supply store | Folders and printer paper for the tutoring room | Office expenses | Program services | Youth education grant | $48.20 | Attached |
| Example: 3/9 | Hotel | Lodging for the state nonprofit finance conference | Travel | Management and general | Unrestricted | $189.00 | Attached |
| Example: 3/15 | Printer | Spring appeal letters | Advertising and promotion | Fundraising | Unrestricted | $312.75 | Attached |
Keep the category list short. I'd rather see one supplies account with a class for each program than a separate supplies account for every program.
A common year-end problem is a mismatch between how your software records expenses and how Form 990 needs them, which forces manual reclassification.
Start with a nonprofit chart of accounts aligned with Form 990 and FASB ASC 958. Map each natural expense account to its Part IX line, then use segment codes or classes to capture the function, so at year-end you run a report instead of recoding every expense.
Name each account in plain words your finance and program staff both understand. When two teams use different terms for the same expense, budget comparisons become unreliable and audit preparation gets painful.
Shared costs are one of the trickiest areas of nonprofit expense reporting. Rent, utilities, the executive director's salary, and general IT tools often benefit more than one functional category, and inconsistent allocation leads to inaccurate functional expense statements or auditor concerns.
A written cost allocation policy solves this. It should document methods approved by management or the audit committee, use time studies or activity logs for personnel costs, and apply reasonable bases such as square footage for occupancy or FTE count for shared services.
For example, if your executive director earns $120,000 and spends approximately 60% of their time on program oversight and 40% on administration, $72,000 flows to program expenses and $48,000 flows to management and general. Document that split in writing, apply it consistently, and review it each year. A method that was accurate two years ago may no longer reflect how your organization actually operates.
Grants and donor-restricted gifts add usage requirements that must show up in how you classify expenses. For organizations managing multiple funding streams, KleerCard's restricted funds tracking tools make this easier.

Expense reporting feeds the nonprofit financial statements: the Statement of Activities, the Statement of Financial Position, and the Statement of Cash Flows, plus the analysis of expenses by nature and function, which many nonprofits present as a separate Statement of Functional Expenses.
That analysis is unique to nonprofits. It's a matrix that shows what you spent money on (salaries, supplies, and rent) and the purpose behind each expenditure (program, admin, and fundraising), which is the same nature-by-function view as the table above.
Any time a staff member, volunteer, or board member spends personal money on behalf of your organization, you need a formal reimbursement process. For employees, an accountable plan is what keeps those reimbursements out of taxable wages.
The IRS requires accountable plans to meet three specific criteria: employees must prove a business connection, offer adequate documentation, and return any unsubstantiated reimbursements. IRS Publication 463 treats accounting for expenses within 60 days and returning any excess within 120 days as a reasonable period. Reimbursements that miss these rules are treated as paid under a nonaccountable plan and reported as wages on the employee's Form W-2.
For mileage, the 2026 IRS standard mileage rates are 72.5 cents per mile for business use and 14 cents per mile driven in service of charitable organizations. The charitable rate is set by statute. It's the rate a volunteer can use to deduct unreimbursed miles driven for your nonprofit, as IRS Publication 526 explains, so it helps to share it with volunteers who drive for you without being reimbursed.
I highly recommend keeping reimbursements out of payroll. Set up the person you're reimbursing as a vendor and pay them by ACH, so they can submit a reimbursement and have the money in their account the next day. Mileage is a good example of a cost a card can't replace, and quick repayment goes a long way with volunteers.
The IRS doesn't require a written accountable plan, but I'd write one anyway and share it with every employee and volunteer, along with a nonprofit expense reimbursement policy. It removes ambiguity and gives you a defensible record in an audit.

Many nonprofits save their energy for the annual audit and Form 990, then find unreconciled accounts, missing documentation, and classification errors at year-end.
A disciplined month-end close prevents that scramble. Close the books within 10 business days of month-end: reconcile bank accounts, credit cards, and loans, review receivables aging, and classify expenses by nature and function as you record them.
The close gets shorter when expenses are coded as they happen and receipts are captured at the time of purchase. Build those habits into a monthly rhythm and year-end becomes a review of work already done.
Want to see how KleerCard can shorten your close? Schedule a free demo.
The most effective nonprofit expense management happens before a transaction occurs. Reporting after the fact matters, but preventing misclassified spending is better. A clear expense policy, reimbursement policy, and credit card policy help your team tell necessary spending from inappropriate spending.
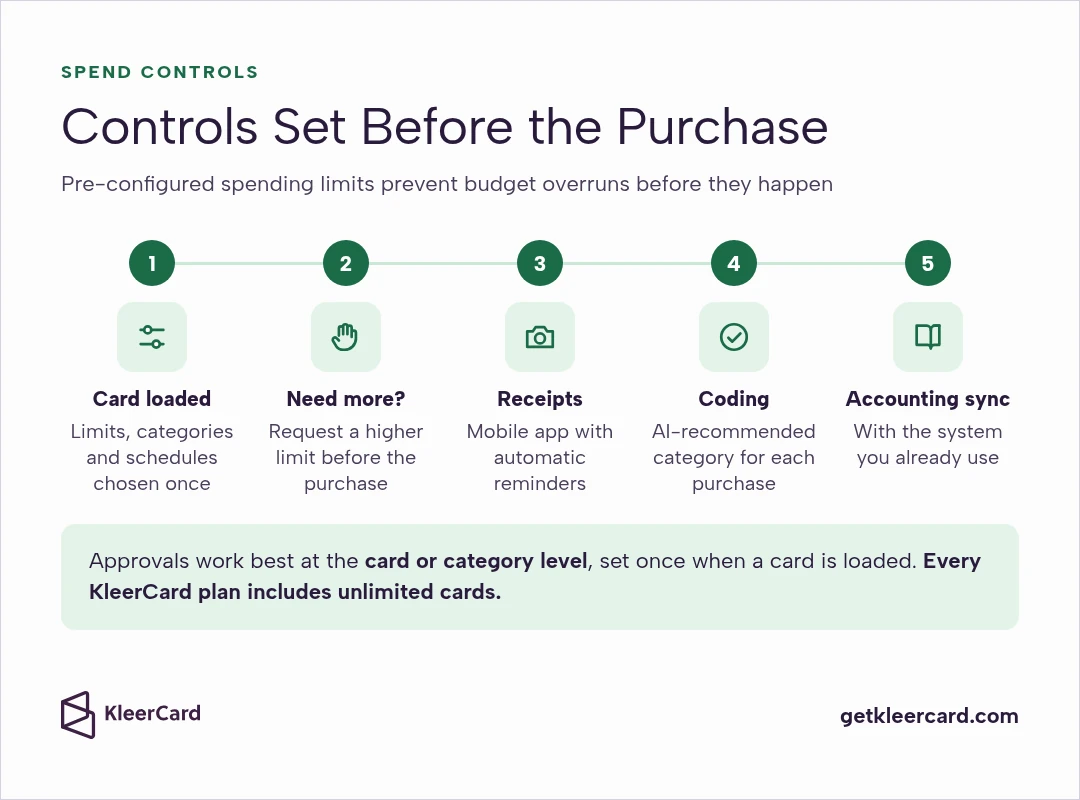
Approvals work best at the card or category level, set once when a card is loaded and its limits, categories, and schedules are chosen, and when someone needs more, they request a higher limit before the purchase. Virtual and physical cards with pre-configured spending limits prevent budget overruns before they happen.
For churches and faith-based nonprofits, stewardship is a core value as much as a financial principle, and your systems should reflect it.
In 2026, receipt capture and coding tools have made paper receipts and spreadsheets optional for most teams. Tools using OCR can pull data straight from receipts and invoices, and integrating expense systems with accounting software removes manual data transfers.
Automation works best when it solves a specific problem. Start with the most repetitive steps, usually receipt collection and coding, and build from there.
When evaluating nonprofit expense management software, look for these core capabilities:
Form 990 is one of the most public documents your nonprofit produces, read by donors, watchdogs, and grantors. The way your expenses appear on this form, guided by the IRS Form 990 instructions, shows readers how your organization spends its money.
Churches and their integrated auxiliaries are among the organizations the IRS exempts from filing an annual return. Many still keep their books in the same nature-by-function format, because their boards and donors expect the same clear picture.
Form 990 preparation starts in January. Program narratives should clearly show mission impact, expense allocations should reflect reasonable program spending, and compensation should align with comparable organizations. Capture executive compensation data and your conflict-of-interest and whistleblower policy confirmations as the year goes, not in March.
Restricted funds need the same year-round attention. Track spending against approved budgets and expiration dates, and keep the original agreements with the expense records. A grant report showing funds spent outside approved categories can damage funder relationships and trigger claw-back requirements.
Your board can't meet its fiduciary responsibility without financial information that is clear, timely, and actionable. A 40-page audit report sent the day before a meeting is hard to use for governance. A concise package with the right metrics and a plain-language narrative gives the board something to act on.
An effective board financial package typically includes budget versus actual comparisons broken down by program, key metrics like cash position and net assets, restricted fund balances, and a brief narrative explaining significant variances. A nonprofit budget template is a good starting point for the budget side.
When board members understand the numbers, they ask better questions and spot early warning signs.
Every donor is trusting you to use their gift wisely. Accurate expense reporting honors that trust and shows donors, board members, and grantmakers that your nonprofit is responsible and mission-focused.
That's especially true for churches and faith-driven organizations, and it starts with the people making purchases.
Lisa, an accountant at a church that uses KleerCard, told us: The ability for employees to upload their receipts and code purchases on the run has been a huge blessing! KleerCard has significantly decreased the amount of time spent reconciling.
When receipts and coding happen at the moment of purchase, leadership spends less time chasing paperwork and more time on the work that actually matters.
Use this to see where your organization stands today:
Expense Categories Keep a short list of natural categories that maps to Form 990 Part IX, and code every expense to a category, a function, and a fund or grant when it happens.
Chart of Accounts Align account codes with Form 990 categories and FASB ASC 958. Use segment codes or classes to capture the functional dimension.
Cost Allocation Policy Document a written methodology approved by your audit committee or leadership. Apply it consistently and review it every year.
Accountable Plan Put your reimbursement policy in writing and train your team on the 60-day documentation and 120-day excess return safe harbors. Use the 2026 business rate of 72.5 cents per mile for employee mileage, and let volunteers who drive unreimbursed know about the 14 cents per mile charitable rate.
Monthly Close Set a firm close date within 10 business days of month-end, with reconciliation and functional classification built into the routine.
Spend Controls Set card limits, categories, and written spending policies before expenses occur, and issue virtual and physical cards by role and department.
Automation Find the biggest manual bottlenecks, usually receipt collection and coding, and choose a tool that works with your accounting software.
Form 990 Preparation Start capturing program narratives, restricted fund documentation, compensation data, and governance policy confirmations in January.
Board Reporting Lead your board package with key metrics and plain-language explanations, with detail available on request.
KleerCard was built for nonprofit and church finance teams.
Physical and virtual cards with configurable spending limits give your team the freedom to spend on mission while protecting against overspending, and every plan includes unlimited cards. Limits, categories, and schedules are set when a card is loaded, so each person has a budget that fits how they actually spend.
AI-recommended coding suggests the right category for each purchase, and receipts come in through the mobile app with automatic reminders. On paid plans, bill pay and reimbursements bring card, vendor, and reimbursement spending into one platform, so reconciliation and reporting move faster. We're also building KleerFi, fund accounting for nonprofits, and you're welcome to join the waitlist.
If expense reporting is taking more time than it should, or a year-end audit has you feeling unprepared, KleerCard can help.
Nonprofits sort every expense two ways: by nature, meaning what was bought, such as salaries, rent, or supplies, and by function, meaning why it was spent: program services, management and general, or fundraising. A good category list mirrors the natural expense lines on Form 990 Part IX.
The three functional categories on Form 990 are program services, management and general, and fundraising. Program expenses tie directly to mission-related activities, management and general expenses relate to running the organization as a whole, and fundraising expenses cover soliciting donations and managing donor relationships. 501(c)(3) and 501(c)(4) organizations complete all three columns in Part IX.
Form 990 Part IX lists natural expense lines 1 through 24, with the total on line 25.
Those lines run from grants (lines 1 to 3) and compensation, benefits, and payroll taxes (lines 5 to 10) through fees for services, advertising, office expenses, technology, occupancy, travel, conferences, interest, depreciation, and insurance (lines 11 to 23), with line 24 for other expenses and line 25 for the total. Each line is split across the program, management and general, and fundraising columns.
A 501(c)(3) can spend on anything that furthers its exempt purpose, including programs, staff pay, rent, insurance, and fundraising. The IRS rules out spending that benefits insiders privately and any political campaign activity for or against a candidate, and lobbying can't be a substantial part of what the organization does.
A tax-exempt nonprofit generally doesn't pay federal income tax, so it doesn't write off expenses the way a business does. It still reports its expenses by function on Form 990. The exception is unrelated business income: an organization with $1,000 or more of gross income from an unrelated business files Form 990-T, where related expenses come into play.
Many boards and donors ask this, and it helps to know that the IRS doesn't set a program spending ratio. The BBB Wise Giving Alliance standards ask charities to spend at least 65% of total expenses on program activities, and many donors use that as a benchmark.
An accountable plan is a reimbursement structure that meets IRS requirements under Treasury Regulation 1.62-2, allowing nonprofits to reimburse employees for business expenses without those payments being classified as taxable wages.
To qualify, expenses must have a clear business connection, be accounted for within a reasonable period, and any excess advances must be returned within a reasonable period. The IRS treats 60 days to document and 120 days to return excess as reasonable.
According to the 2026 IRS standard mileage rates, the rate is 72.5 cents per mile for business use and 14 cents per mile for charitable use. The charitable rate is set by statute, and it's the rate volunteers can use to deduct unreimbursed miles they drive for your organization.
Reconciling every month is the best practice, and it's the habit that makes everything else easier. Closing the books within 10 business days of month-end and classifying expenses by both natural and functional categories as you record them prevents the year-end scramble that plagues many organizations.
Good documentation lets anyone outside the purchase understand it. The IRS requires receipts for lodging and for any expense of $75 or more, and a written record of the date, amount, place, and business purpose covers smaller items.
Keep a mileage log at or near the time of each trip. Many nonprofits ask for a receipt for everything as policy, and any unspent travel advance goes back within a reasonable period.
Automation takes the most repetitive steps off your team's plate. Tools using OCR can pull data straight from receipts and invoices, card-level controls replace paper sign-offs, and integration with accounting software removes manual data transfers. Automated systems also create digital records that auditors can quickly review.
The 33% rule people usually mean is the IRS public support test, which helps decide whether a 501(c)(3) is a public charity. Over a five-year period, the organization normally needs at least 33 1/3% of its total support to come from the general public, government, and other public charities. If that share is lower, a 10% facts-and-circumstances test may still apply. This is about how you are supported, not how you set up funds or report expenses. The IRS does not require a set share of expenses to go to programs. For program spending benchmarks used by watchdogs, see What percentage of a nonprofit's expenses should go to programs? above. Those benchmarks are not IRS law.
Most tax-exempt nonprofits file an annual Form 990, 990-EZ, or 990-N. GAAP financial statements for a nonprofit include a statement of financial position, a statement of activities, a statement of cash flows, and a statement of functional expenses (or an analysis of expenses by nature and function). Those statements and the Form 990 work are covered in The Four Financial Statements That Support Expense Reporting and the Form 990 section above.
It depends on your size, whether you need true fund accounting, and your budget. Compare tools in the nonprofit accounting software guide. KleerCard is spend management. It doesn't replace your general ledger.
Good expense reporting starts small: a short category list, a function on every expense, and a close every month. Get those three right and Form 990, the board package, and the next grant report come together far faster.
If you'd like help setting up categories and controls that fit how your team actually spends, we'd love to show you around. You can get started with KleerCard today, or schedule a demo and we'll walk through it together.
Speak to a member of our team and we can have you up and running in minutes, not weeks.